


Settlement speed
Most transfers to Bangladesh settle in minutes to hours via local rails - not days through correspondent banks.
Move funds from North America to Bangladesh with transparent FX, local payment rails, and real-time tracking across every supported country on this route.
Fast SettlementBuilt for faster delivery across Bangladesh
Transparent PricingKnow fees and FX rates before you send
Regional CoverageSend to 100+ countries with local payout rails - bKash, Nagad, and Bangladeshi bank transfers
 USD
 BDT
Send from North America to Bangladesh with delivery timelines shown upfront on every transfer across 2 origin and 0 destination countries.
Most supported routes settle within minutes to hours via local rails and stablecoin infrastructure.
Live FX and fees on every North America → Bangladesh route - no hidden spreads or surprise deductions.
Know the final amount, fees, and FX rate before funds leave North America or arrive in Bangladesh.
Monitor every payment from North America to Bangladesh in real time - from initiation through payout across the corridor.
Corridor-level status updates from initiation through local payout in Bangladesh.
Speed up North America → Bangladesh settlement with stablecoin infrastructure bridging both markets.
Combine local payment rails in North America with faster settlement into Bangladesh payout networks.
Most transfers to Bangladesh settle in minutes to hours via local rails - not days through correspondent banks.
See live USD to BDT exchange rates and fees upfront before you confirm your transfer.
Real-time status updates from funding in North America through delivery in Bangladesh.
Deliver to bKash, Nagad, and Bangladeshi bank transfers that people in Bangladesh use daily, funded from North America - not generic wire-only endpoints.
KYC, KYB, and beneficiary verification aligned with regulations on both sides of the corridor.
Send from 2 countries across North America using familiar local payment methods.
Enter the amount in United States dollar
Add your recipient's bKash or bank account - for Bangladesh this is typically full name and bKash, Nagad, or Bangladeshi bank account information
Review the exchange rate, fees, and estimated delivery time
Send and track the payment in real time
Set up your North America to Bangladesh corridor in just a few steps.
bKash is Bangladesh's dominant mobile financial service with over 65 million registered accounts and the widest agent network in the country. Users rely on bKash for P2P transfers, merchant QR payments, utility bills, school fees, and e-commerce checkout. For businesses, bKash is often the single highest-impact payment method to integrate—its brand is synonymous with mobile money in Bangladesh, and absence at checkout is a direct conversion penalty. International send and receive products terminating into bKash match the UX expectations of Bangladesh's largest financial user base.
Minutes
Nagad is Bangladesh Post Office's mobile financial service and bKash's primary competitor, with rapid adoption driven by government disbursements, social safety net payments, and competitive merchant incentives. Nagad excels at reaching users in semi-urban and rural areas where post office brand trust matters—particularly for remittance receive in Sylhet, Rangpur, and coastal districts. Platforms supporting both bKash and Nagad maximize addressable market coverage across Bangladesh's 172 million population and avoid alienating users loyal to either wallet ecosystem.
Minutes
Rocket, operated by Dutch-Bangla Bank, is one of Bangladesh's pioneering MFS platforms with deep roots in bank-linked mobile banking across 172 million population. It remains popular among users who prefer bank-backed wallets and among certain merchant categories in Dhaka and Chattogram. Rocket supports cash-in and cash-out through DBBL agents and ATMs, making it a reliable rail for RMG payroll-adjacent flows and users transitioning between cash and digital money in Bangladesh's export economy.
Minutes to hours
Commercial bank transfers remain essential for B2B settlement, property transactions, and higher-value consumer payments. Leading institutions including BRAC Bank, City Bank, and Islami Bank Bangladesh serve corporate treasuries, exporters, and middle-class account holders. For international platforms, supporting bank transfer collection and payout in BDT provides a critical backstop for transactions that exceed MFS limits or require formal banking records.
Same business day
Upay is a growing mobile financial service backed by United Commercial Bank, targeting digital-native users and merchant partnerships across Bangladesh's $4.8 billion e-commerce market. While smaller than bKash and Nagad, Upay adds incremental coverage among UCB customers and urban professionals in Dhaka. Including Upay in a multi-rail strategy future-proofs payment acceptance as Bangladesh's MFS market continues to diversify beyond two dominant players serving the seventh-largest remittance receiver nation.
Minutes to hours
Send with the payment methods people use across Bangladesh.

Direct deposit to local bank accounts where available

Wallet delivery on supported routes

Faster payout rails where available in Bangladesh
Offer local payout options recipients trust across Bangladesh.
This North America to Bangladesh route combines TransFi's cross-border infrastructure with local payout coverage via bKash, Nagad, and Bangladeshi bank transfers. Whether you're disbursing payroll, paying suppliers, or sending to family, transfers typically settle in minutes to hours with live USD-to-BDT rates shown upfront.
Explore live rates and coverage for the North America → Bangladesh corridor, including bKash, Nagad, and Bangladeshi bank transfers and many more.
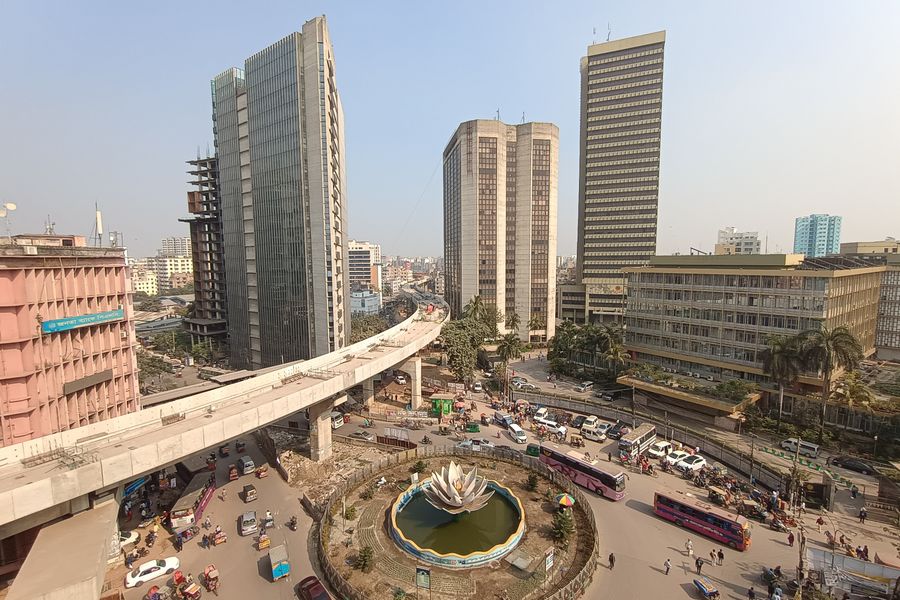
Sending money to Bangladesh from North America sits at the intersection of one of the world's most dynamic payment corridors and one of its most digitally sophisticated origin markets. US technology companies, Canadian enterprises, Silicon Valley startups, New York financial services firms, and North American marketplaces increasingly employ talent, source goods, and support families in Bangladesh—a market of 172 million people where bKash and Nagad mobile financial services; Rocket wallet; and commercial bank accounts define how recipients actually receive and spend funds. Whether you are a North American enterprise paying suppliers in Dhaka, a platform disbursing creator earnings, or part of Bangladeshi-American communities in New York and Detroit, and Bangladeshi workers across the US and Canada sending regular family support, recipients expect fast delivery in BDT through payment channels they trust—not slow correspondent wires that arrive days later with opaque FX deductions.
Traditional international transfers from the United States, Canada, and cross-border North American enterprises often route through legacy banking chains that add hidden spreads, provide limited payout method choice, and offer poor end-to-end tracking. Bangladesh beneficiaries have moved decisively toward mobile-first financial infrastructure: bKash, Nagad, Rocket, and commercial banks power daily commerce, bill payments, and peer-to-peer transfers across Dhaka, Chattogram, Sylhet, and Gazipur industrial zones and beyond. A send product that terminates only into unfamiliar banking channels creates support burden, failed deliveries, and churn—especially when competitors credit bKash wallets within minutes.
TransFi modernizes North America-to-Bangladesh outbound payments by combining cross-border compliance under FinCEN, OFAC, state-level money transmitter rules, and FINTRAC requirements in Canada with localized last-mile delivery through bKash and Nagad mobile financial services; Rocket wallet; and commercial bank accounts. Senders fund transfers in USD, CAD, and other major North American currencies via API with webhook-driven status updates, embedded beneficiary verification, and transparent all-in pricing. One integration covers Bangladesh alongside other TransFi priority corridors—Indonesia, Philippines, Malaysia, Thailand, Pakistan, and Bangladesh—eliminating fragmented vendor relationships across remittance, wallet, and FX layers that drain engineering resources.
The economic case for modern send infrastructure is compelling. Bangladesh receives Gulf and Southeast Asian worker remittances, RMG wage support, and humanitarian disbursements, and US-ASEAN commercial partnerships, North American import networks, and cross-border B2B supply chains generate sustained B2B payment volume alongside remittance flows. Bangladeshi-American communities in New York and Detroit, and Bangladeshi workers across the US and Canada represent high-frequency send segments where delivery speed and method choice directly determine customer retention. Platforms paying remote teams in ready-made garments and related sectors need recurring BDT disbursement on predictable schedules with per-transaction audit trails suitable for North American finance teams.
Compliance is not optional on this corridor. FinCEN, OFAC, state-level money transmitter rules, and FINTRAC requirements in Canada requirements on the sending side must align with destination-country AML and payment regulations without creating friction that drives users to informal channels. TransFi embeds KYC for individual senders, KYB for business clients, and beneficiary verification within API-integrated flows—structured to scale with transaction volume while maintaining auditability for regulated fintech, payroll, and marketplace use cases operating from the United States, Canada, and cross-border North American enterprises.
Choosing TransFi means treating North America-to-Bangladesh sends as core product infrastructure rather than an afterthought. Faster delivery through bKash, Nagad, Rocket, and commercial banks, transparent FX, compliance-ready orchestration, and unified reconciliation give North American senders a competitive edge in one of emerging markets' most important payment corridors.
Senders on the North America to Bangladesh corridor disburse through bKash, Nagad, and Bangladeshi bank transfers and other trusted local payout rails. The North America-to-Bangladesh send corridor reflects structural forces shaping global labor mobility, digital commerce, and cross-border B2B trade. On the origin side, the United States, Canada, and cross-border North American enterprises generate outbound volume from Bangladeshi-American communities in New York and Detroit, and Bangladeshi workers across the US and Canada, Silicon Valley, Seattle, Austin, Toronto, and Vancouver tech ecosystems hiring globally, and enterprises with supply chain relationships in ready-made garments, pharmaceuticals, agriculture, shipbuilding, and IT outsourcing. On the destination side, Bangladesh, with the seventh-largest remittance-receiving nation globally with a $4.8 billion e-commerce market, has produced payment behavior centered on bKash, Nagad, Rocket, and commercial banks—rails that international senders must connect to for satisfactory recipient experiences.
Understand what drives this corridor - then send from North America to Bangladesh in minutes.
Three things that define this route
Sending money to Bangladesh from North America sits at the intersection of one of the world's most dynamic payment corridors and one of its most digitally sophisticated origin markets. US technology companies, Canadian enterprises, Silicon Valley startups, New York financial services firms, and North American marketplaces increasingly employ talent, source goods, and support families in Bangladesh—a market of 172 million people where bKash and Nagad mobile financial services; Rocket wallet; and commercial bank accounts define how recipients actually receive and spend funds. Whether you are a North American enterprise paying suppliers in Dhaka, a platform disbursing creator earnings, or part of Bangladeshi-American communities in New York and Detroit, and Bangladeshi workers across the US and Canada sending regular family support, recipients expect fast delivery in BDT through payment channels they trust—not slow correspondent wires that arrive days later with opaque FX deductions.
The North America-to-Bangladesh send corridor reflects structural forces shaping global labor mobility, digital commerce, and cross-border B2B trade. On the origin side, the United States, Canada, and cross-border North American enterprises generate outbound volume from Bangladeshi-American communities in New York and Detroit, and Bangladeshi workers across the US and Canada, Silicon Valley, Seattle, Austin, Toronto, and Vancouver tech ecosystems hiring globally, and enterprises with supply chain relationships in ready-made garments, pharmaceuticals, agriculture, shipbuilding, and IT outsourcing. On the destination side, Bangladesh, with the seventh-largest remittance-receiving nation globally with a $4.8 billion e-commerce market, has produced payment behavior centered on bKash, Nagad, Rocket, and commercial banks—rails that international senders must connect to for satisfactory recipient experiences.
TransFi modernizes North America-to-Bangladesh outbound payments by combining cross-border compliance under FinCEN, OFAC, state-level money transmitter rules, and FINTRAC requirements in Canada with localized last-mile delivery through bKash and Nagad mobile financial services; Rocket wallet; and commercial bank accounts. Senders fund transfers in USD, CAD, and other major North American currencies via API with webhook-driven status updates, embedded beneficiary verification, and transparent all-in pricing. One integration covers Bangladesh alongside other TransFi priority corridors—Indonesia, Philippines, Malaysia, Thailand, Pakistan, and Bangladesh—eliminating fragmented vendor relationships across remittance, wallet, and FX layers that drain engineering resources.
From payouts and collections to checkout, treasury, and stablecoin rails - TransFi powers it all through a single integration.
Bangladeshi-American communities in New York and Detroit, and Bangladeshi workers across the US and Canada send regular support to families in Dhaka, Chattogram, Sylhet, and Gazipur industrial zones and across Bangladesh. Recipients rely on bKash for groceries, school fees, rent, and daily expenses—often expecting funds within hours, not days. TransFi-powered send flows convert USD origin funds and deliver to bKash and Nagad mobile financial services; Rocket wallet; and commercial bank accounts with transparent fees and real-time tracking senders can share with recipients. Faster, cheaper delivery compared to legacy remittance chains increases send frequency and builds loyalty among diaspora communities who compare providers actively within social networks, worker associations, and community organizations across the United States, Canada, and cross-border North American enterprises.
Silicon Valley, Seattle, Austin, Toronto, and Vancouver tech ecosystems hiring globally employ developers, designers, customer experience specialists, and consultants across Bangladesh's ready-made garments, pharmaceuticals, agriculture, shipbuilding, and IT outsourcing sectors. Monthly payroll requires reliable BDT delivery to bKash wallets or bank accounts on fixed schedules with per-employee traceability. TransFi automates recurring sends with beneficiary KYC, configurable schedules, and webhook confirmation for HR and finance systems integrated with North American enterprise tools. Replacing manual wire batches reduces errors, shortens settlement time, and gives employees predictable access to earnings through payment channels they already use daily in Dhaka, Chattogram, Sylhet, and Gazipur industrial zones.
Trade relationships shaped by US-ASEAN commercial partnerships, North American import networks, and cross-border B2B supply chains create sustained demand for North American businesses paying Bangladesh suppliers, manufacturers, and service providers in BDT. bKash and Nagad mobile financial services; Rocket wallet; and commercial bank accounts support invoice settlement where wallet balances may be insufficient for larger B2B amounts. TransFi enables cross-border sends tied to invoice references with audit trails suitable for North American accounting and tax documentation. Suppliers in Dhaka, Chattogram, Sylhet, and Gazipur industrial zones receive funds through familiar domestic channels, strengthening supply chain relationships and reducing payment-related delays in goods shipment and service delivery across ready-made garments, pharmaceuticals, agriculture, shipbuilding, and IT outsourcing.
Global platforms operating from North America owe earnings to Bangladesh sellers, freelancers, creators, and gig workers who expect timely payout in BDT through bKash or bank channels. Delayed or failed transfers drive seller churn and reputational damage in competitive ready-made garments, pharmaceuticals, agriculture, shipbuilding, and IT outsourcing markets. TransFi routes platform-initiated sends to bKash and Nagad mobile financial services; Rocket wallet; and commercial bank accounts through a unified API, supporting micro-payouts at scale and larger periodic settlements. Embedded verification satisfies compliance under FinCEN, OFAC, state-level money transmitter rules, and FINTRAC requirements in Canada without forcing beneficiaries through disconnected onboarding portals, improving platform liquidity and seller retention across Bangladesh.
Whatever your use case, TransFi moves money from North America to Bangladesh.
Choose your specific origin country - 2 supported markets across North America link to dedicated North America → Bangladesh corridor pages.
Pick your origin country and start sending from North America to Bangladesh.
Find the right route for your cross-border payments - search by country or region and open the corridor that matches your needs.
Send North America to Indonesia corridor
Send Latin America to Indonesia corridor
Send Africa to Indonesia corridor
Send Asia Pacific to Indonesia corridor
Send Europe to Indonesia corridor
Send Middle East & North Africa to Indonesia corridor
Send North America to Philippines corridor
Send Latin America to Philippines corridor
Send Africa to Philippines corridor
$5B+
transaction volume projected
2M+
users served globally
100+
enterprise clients
Global compliance coverage | Enterprise-grade infrastructure | 24/7 support
How fast can TransFi deliver funds from North America to Bangladesh?
Delivery speed depends on the selected last-mile method, compliance checks at send time, and the funding source used on the North American side. Transfers terminating into bKash wallets and instant bank rails typically confirm within minutes to a few hours once the cross-border leg is approved—substantially faster than traditional correspondent wire chains that may take three to five business days from the United States, Canada, and cross-border North American enterprises. TransFi provides real-time status updates via API webhooks so senders and platforms can notify recipients proactively. Exact timelines vary by amount, beneficiary type, verification tier, and local rail availability in Dhaka, Chattogram, Sylhet, and Gazipur industrial zones.
Which payout methods are supported for sends to Bangladesh?
TransFi supports payout to bKash and Nagad mobile financial services; Rocket wallet; and commercial bank accounts, giving senders flexibility to match recipient preferences across Bangladesh. Wallet payouts suit beneficiaries who manage daily spending through mobile apps, while bank transfers handle higher-value B2B payments and recipients who prefer account credits. Senders specify beneficiary details during onboarding or via API, with verification steps embedded to meet compliance requirements on both the North American origin and Bangladesh destination sides. This method breadth improves reach compared to bank-only outbound providers operating from North America.
What currencies can I send from North America when paying Bangladesh recipients?
TransFi supports cross-border sends originating from USD, CAD, and other major North American currencies and stablecoin treasury configurations, with conversion into BDT for local delivery. Businesses operating multi-currency treasuries across the United States, Canada, and cross-border North American enterprises can fund sends from their preferred operating currency depending on account setup. FX rates and fees are disclosed at initiation so North American finance teams can budget accurately and compare all-in cost against alternative providers. This model suits enterprises, platforms, and remittance operators that consolidate international liquidity before local disbursement to Bangladesh.
What compliance is required to send money from North America to Bangladesh?
TransFi embeds KYC for individual senders and KYB for business clients, alongside beneficiary verification aligned with FinCEN, OFAC, state-level money transmitter rules, and FINTRAC requirements in Canada and Bangladesh cross-border payment requirements. Required documentation may include identity verification, proof of address, source-of-funds declarations for higher-value transfers, and business incorporation records for corporate senders operating from the United States, Canada, and cross-border North American enterprises. These checks run through API-integrated flows rather than redirecting users to disconnected portals. Compliance is structured to scale with transaction volume while maintaining auditability for regulated fintech, payroll, marketplace, and B2B use cases on the North America-to-Bangladesh corridor.
Fast, transparent, and built for modern cross-border payments from North America to Bangladesh
 Global Payments. Delivered Locally - Send, receive, and convert funds across 100+ countries.
 UAEUSA
 Poland
 Canada
 Bahamas
 Indonesia
 Australia
 Copyright ©2026 TransFi | All Rights Reserved


