Settlement speed
Most transfers to Bangladesh settle in minutes to hours via local rails - not days through correspondent banks.
Move funds from Middle East & North Africa to Bangladesh with transparent FX, local payment rails, and real-time tracking across every supported country on this route.
Fast SettlementBuilt for faster delivery across Bangladesh
Transparent PricingKnow fees and FX rates before you send
Regional CoverageSend to 70+ countries with local payout rails - bKash, Nagad, and Bangladeshi bank transfers
 AED
 BDT
Send from Middle East & North Africa to Bangladesh with delivery timelines shown upfront on every transfer across 5 origin and 0 destination countries.
Most supported routes settle within minutes to hours via local rails and stablecoin infrastructure.
Live FX and fees on every Middle East & North Africa → Bangladesh route - no hidden spreads or surprise deductions.
Know the final amount, fees, and FX rate before funds leave Middle East & North Africa or arrive in Bangladesh.
Monitor every payment from Middle East & North Africa to Bangladesh in real time - from initiation through payout across the corridor.
Corridor-level status updates from initiation through local payout in Bangladesh.
Speed up Middle East & North Africa → Bangladesh settlement with stablecoin infrastructure bridging both markets.
Combine local payment rails in Middle East & North Africa with faster settlement into Bangladesh payout networks.
Most transfers to Bangladesh settle in minutes to hours via local rails - not days through correspondent banks.
See live AED to BDT exchange rates and fees upfront before you confirm your transfer.
Real-time status updates from funding in Middle East & North Africa through delivery in Bangladesh.
Deliver to bKash, Nagad, and Bangladeshi bank transfers that people in Bangladesh use daily, funded from Middle East & North Africa - not generic wire-only endpoints.
KYC, KYB, and beneficiary verification aligned with regulations on both sides of the corridor.
Send from 5 countries across Middle East & North Africa using familiar local payment methods.
Enter the amount in United Arab Emirates dirham
Add your recipient's bKash or bank account - for Bangladesh this is typically full name and bKash, Nagad, or Bangladeshi bank account information
Review the exchange rate, fees, and estimated delivery time
Send and track the payment in real time
Set up your Middle East & North Africa to Bangladesh corridor in just a few steps.
bKash is Bangladesh's dominant mobile financial service with over 65 million registered accounts and the widest agent network in the country. Users rely on bKash for P2P transfers, merchant QR payments, utility bills, school fees, and e-commerce checkout. For businesses, bKash is often the single highest-impact payment method to integrate—its brand is synonymous with mobile money in Bangladesh, and absence at checkout is a direct conversion penalty. International send and receive products terminating into bKash match the UX expectations of Bangladesh's largest financial user base.
Minutes
Nagad is Bangladesh Post Office's mobile financial service and bKash's primary competitor, with rapid adoption driven by government disbursements, social safety net payments, and competitive merchant incentives. Nagad excels at reaching users in semi-urban and rural areas where post office brand trust matters—particularly for remittance receive in Sylhet, Rangpur, and coastal districts. Platforms supporting both bKash and Nagad maximize addressable market coverage across Bangladesh's 172 million population and avoid alienating users loyal to either wallet ecosystem.
Minutes
Rocket, operated by Dutch-Bangla Bank, is one of Bangladesh's pioneering MFS platforms with deep roots in bank-linked mobile banking across 172 million population. It remains popular among users who prefer bank-backed wallets and among certain merchant categories in Dhaka and Chattogram. Rocket supports cash-in and cash-out through DBBL agents and ATMs, making it a reliable rail for RMG payroll-adjacent flows and users transitioning between cash and digital money in Bangladesh's export economy.
Minutes to hours
Commercial bank transfers remain essential for B2B settlement, property transactions, and higher-value consumer payments. Leading institutions including BRAC Bank, City Bank, and Islami Bank Bangladesh serve corporate treasuries, exporters, and middle-class account holders. For international platforms, supporting bank transfer collection and payout in BDT provides a critical backstop for transactions that exceed MFS limits or require formal banking records.
Same business day
Upay is a growing mobile financial service backed by United Commercial Bank, targeting digital-native users and merchant partnerships across Bangladesh's $4.8 billion e-commerce market. While smaller than bKash and Nagad, Upay adds incremental coverage among UCB customers and urban professionals in Dhaka. Including Upay in a multi-rail strategy future-proofs payment acceptance as Bangladesh's MFS market continues to diversify beyond two dominant players serving the seventh-largest remittance receiver nation.
Minutes to hours
Send with the payment methods people use across Bangladesh.

Direct deposit to local bank accounts where available

Wallet delivery on supported routes

Faster payout rails where available in Bangladesh
Offer local payout options recipients trust across Bangladesh.
This Middle East & North Africa to Bangladesh route combines TransFi's cross-border infrastructure with local payout coverage via bKash, Nagad, and Bangladeshi bank transfers. Whether you're disbursing payroll, paying suppliers, or sending to family, transfers typically settle in minutes to hours with live AED-to-BDT rates shown upfront.
Explore live rates and coverage for the Middle East & North Africa → Bangladesh corridor, including bKash, Nagad, and Bangladeshi bank transfers and many more.
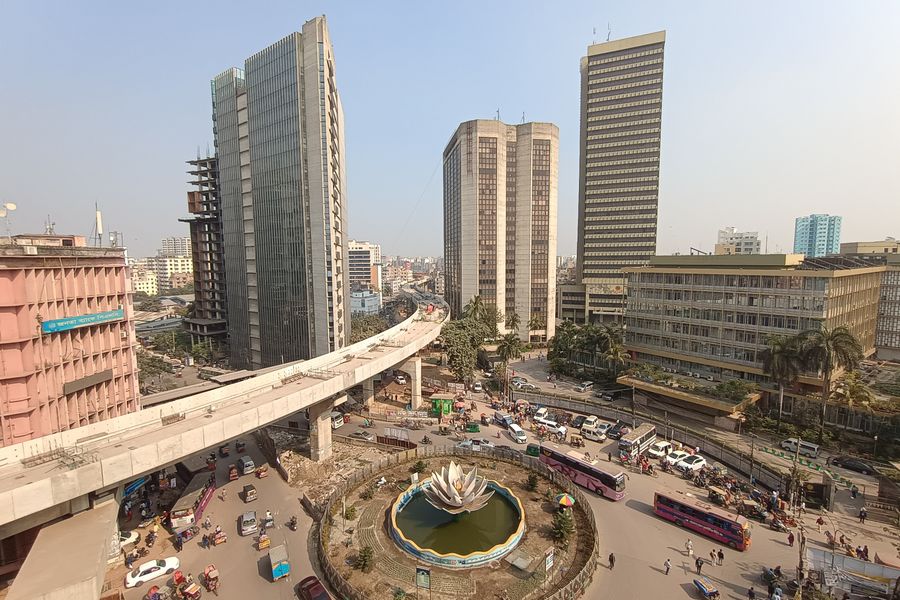
Sending money from Middle East & North Africa to Bangladesh is a corridor where regional origin diversity meets localized last-mile delivery on bKash, Nagad, BEFTN, and bKash rails that 173 million people increasingly treat as default financial infrastructure. Businesses across 15+ origin markets in Middle East & North Africa—funding in UAE dirham, Saudi riyal, Egyptian pound, Moroccan dirham, and Jordanian dinar—need to pay BDT to suppliers, contractors, affiliates, and partners in Dhaka, Chittagong, Sylhet, and beyond without stitching together correspondent banks, opaque FX desks, and disconnected wallet APIs.
MENA enterprises—from Dubai trading houses and Riyadh conglomerates to Cairo manufacturers and Casablanca exporters—route substantial B2B and payroll payments to Asia as Gulf Vision programs and regional diversification accelerate. When Bahraini distributors remitting to Bangladeshi RMG manufacturers initiates a cross-border payment, recipients in Bangladesh expect funds in Bangladeshi taka through channels they already use daily—not a wire notification that requires branch visits or manual wallet top-ups. TransFi connects Middle East & North Africa origin funding to Bangladesh payout orchestration through a unified API with webhook status, beneficiary verification, and treasury settlement in USD, EUR, stablecoins, or origin-region currencies as configured.
Legacy international payment stacks treat Middle East & North Africa-to-Bangladesh as a low-priority SWIFT afterthought. Senders face hidden FX spreads between origin currencies and BDT, multi-day settlement windows, and poor visibility when payments stall at intermediary banks. Bangladesh combines the world's second-largest garment export sector with mobile-money penetration led by bKash. Recipients anchored to bKash and Rocket reject experiences that feel foreign compared to domestic transfers regulated by Bangladesh Bank. TransFi replaces fragmented vendor relationships with corridor-native infrastructure built for emerging-market payment reality.
The economic case for modernizing Middle East & North Africa to Bangladesh sends spans B2B trade settlement, marketplace seller payouts, payroll for remote teams, insurance and aid disbursements, and platform creator earnings. Bahraini distributors remitting to Bangladeshi RMG manufacturers cannot scale if each payout requires manual treasury intervention. API-driven batch sends with per-beneficiary validation, idempotent transaction IDs, and automated retry on transient rail failures give operations teams confidence during high-volume periods. Corridor volumes intensify during Ramadan and Eid disbursement windows, Hajj-related travel payments, and Gulf fiscal quarters when procurement teams settle Asian supplier invoices. TransFi scales elastically so settlement speed does not degrade when volumes surge.
Compliance is non-negotiable on both sides of this corridor. MENA-origin payments require alignment with local FX controls, sanctions screening expectations, and destination-country AML frameworks administered by regulators such as central banks and financial intelligence units. On the Bangladesh destination leg, Bangladesh Bank expects traceable inbound flows with beneficiary identification aligned to local payment system rules. TransFi embeds sender KYB, beneficiary verification, and sanctions screening into API workflows rather than redirecting users to disconnected portals. Audit trails support finance teams reconciling BDT payouts against ERP records and transfer-pricing documentation for multinational groups operating across Middle East & North Africa and Bangladesh.
Speed and cost determine provider selection. Where traditional wires may take three to five business days with $25–40 in opaque fees, TransFi routes Middle East & North Africa-origin liquidity through optimized FX and localized Bangladesh termination—often delivering to bKash or bank endpoints within minutes to hours once compliance checks complete. Senders see all-in pricing at initiation: disclosed fees, live FX, and expected delivery windows. That transparency wins repeat usage in competitive corridors where Bahraini distributors remitting to Bangladeshi RMG manufacturers compares providers on delivered value, not marketing claims.
Senders on the Middle East & North Africa to Bangladesh corridor disburse through bKash, Nagad, and Bangladeshi bank transfers and other trusted local payout rails. The Middle East & North Africa to Bangladesh send corridor reflects structural shifts in global trade, remote work, and platform economics. MENA enterprises—from Dubai trading houses and Riyadh conglomerates to Cairo manufacturers and Casablanca exporters—route substantial B2B and payroll payments to Asia as Gulf Vision programs and regional diversification accelerate. Simultaneously, Bangladesh exports ready-made garments and jute and agricultural exports, drawing procurement teams in United Arab Emirates and neighboring Middle East & North Africa markets into recurring BDT payment relationships with vendors in Dhaka and Chittagong.
Understand what drives this corridor - then send from Middle East & North Africa to Bangladesh in minutes.
Three things that define this route
Sending money from Middle East & North Africa to Bangladesh is a corridor where regional origin diversity meets localized last-mile delivery on bKash, Nagad, BEFTN, and bKash rails that 173 million people increasingly treat as default financial infrastructure. Businesses across 15+ origin markets in Middle East & North Africa—funding in UAE dirham, Saudi riyal, Egyptian pound, Moroccan dirham, and Jordanian dinar—need to pay BDT to suppliers, contractors, affiliates, and partners in Dhaka, Chittagong, Sylhet, and beyond without stitching together correspondent banks, opaque FX desks, and disconnected wallet APIs.
Origin-side payment behavior in Middle East & North Africa varies by market but converges on demand for digital initiation. UAE bank transfers and wallets; Saudi SARIE instant payments; Egyptian InstaPay; Moroccan bank and mobile channels; regional card acquirers enable senders to fund cross-border payouts locally before FX conversion. Enterprises prefer API batch disbursement integrated with NetSuite, SAP, or regional ERP systems; remittance and gig platforms need white-label flows with competitive UAE dirham-to-BDT rates. TransFi abstracts this origin complexity while presenting a uniform integration to product teams.
Legacy international payment stacks treat Middle East & North Africa-to-Bangladesh as a low-priority SWIFT afterthought. Senders face hidden FX spreads between origin currencies and BDT, multi-day settlement windows, and poor visibility when payments stall at intermediary banks. Bangladesh combines the world's second-largest garment export sector with mobile-money penetration led by bKash. Recipients anchored to bKash and Rocket reject experiences that feel foreign compared to domestic transfers regulated by Bangladesh Bank. TransFi replaces fragmented vendor relationships with corridor-native infrastructure built for emerging-market payment reality.
From payouts and collections to checkout, treasury, and stablecoin rails - TransFi powers it all through a single integration.
Bahraini distributors remitting to Bangladeshi RMG manufacturers require dependable BDT invoice settlement to vendors in Dhaka, Chittagong, and secondary industrial zones. TransFi routes Middle East & North Africa-origin funding—via UAE bank transfers and wallets and treasury currencies—through optimized FX into bKash and bank termination with invoice references captured for ERP reconciliation. Finance teams in United Arab Emirates schedule batch runs aligned to Bangladesh business hours, reducing supplier friction that delays shipment of ready-made garments and jute and agricultural exports goods back to Middle East & North Africa buyers. Multinational procurement groups centralize Bangladesh payouts through TransFi's API, replacing ad-hoc wire initiation that lacked beneficiary validation and status visibility. Proof-of-payment documents support audit requirements under MENA-origin payments require alignment with local FX controls, sanctions screening expectations, and destination-country AML frameworks administered by regulators such as central banks and financial intelligence units. Suppliers receive BDT on rails they trust—bKash for SME vendors, instant bank transfer for larger manufacturers—strengthening supply relationships across the Middle East & North Africa to Bangladesh trade lane. Three-way matching between purchase orders, goods receipts, and TransFi payment confirmations closes the loop for Bangladesh accounts payable teams serving Middle East & North Africa parent companies. Automated exception handling flags mismatched beneficiary details before funds leave origin accounts—preventing costly recalls when Bangladesh Bank validation rejects malformed wallet or bank identifiers. Bahraini distributors remitting to Bangladeshi RMG manufacturers require dependable BDT invoice settlement to vendors in Dhaka, Chittagong, and secondary industrial zones. TransFi routes Middle East & North Africa-origin funding—via UAE bank transfers and wallets and treasury currencies—through optimized FX into bKash and bank termination with invoice references captured for ERP reconciliation. Finance teams in United Arab Emirates schedule batch runs aligned to Bangladesh business hours, reducing supplier friction that delays shipment of ready-made garments and jute and agricultural exports goods back to Middle East & North Africa buyers. Multinational procurement groups centralize Bangladesh payouts through TransFi's API, replacing ad-hoc wire initiation that lacked beneficiary validation and status visibility. Proof-of-payment documents support audit requirements under MENA-origin payments require alignment with local FX controls, sanctions screening expectations, and destination-country AML frameworks administered by regulators such as central banks and financial intelligence units. Suppliers receive BDT on rails they trust—bKash for SME vendors, instant bank transfer for larger manufacturers—strengthening supply relationships across the Middle East & North Africa to Bangladesh trade lane.
Companies in Middle East & North Africa employing remote teams across Dhaka, Chittagong, Sylhet, Khulna, Rajshahi need recurring BDT salary delivery via bKash and Nagad. TransFi automates payroll batches with per-employee beneficiary KYC, webhook confirmation for HRIS integration, and transparent BHD-to-BDT FX disclosed before each run. Late payments damage employer brand in Bangladesh's competitive jute and agricultural exports labor market—particularly when workers compare offers from global platforms promising same-day wallet crediting. Gig platforms and agencies disbursing creator, developer, and support earnings from United Arab Emirates to Bangladesh consolidate payout rails through one TransFi integration covering bKash, Nagad, BEFTN, Rocket. Micro-payout economics remain viable at scale with tiered pricing; embedded verification satisfies AML without separate onboarding portals. Operations teams monitor success rates by method and city, optimizing routing when Bangladesh Bank rail maintenance affects specific endpoints. Contractor classification and tax reporting vary across Middle East & North Africa jurisdictions—TransFi transaction metadata supports finance teams documenting cross-border payments to Bangladesh individuals for regulatory filings in United Arab Emirates and peer markets. Payslip integrations can embed TransFi reference numbers so Bangladesh workers reconcile credits against expected BDT amounts on each pay cycle. Companies in Middle East & North Africa employing remote teams across Dhaka, Chittagong, Sylhet, Khulna, Rajshahi need recurring BDT salary delivery via bKash and Nagad. TransFi automates payroll batches with per-employee beneficiary KYC, webhook confirmation for HRIS integration, and transparent BHD-to-BDT FX disclosed before each run. Late payments damage employer brand in Bangladesh's competitive jute and agricultural exports labor market—particularly when workers compare offers from global platforms promising same-day wallet crediting. Gig platforms and agencies disbursing creator, developer, and support earnings from United Arab Emirates to Bangladesh consolidate payout rails through one TransFi integration covering bKash, Nagad, BEFTN, Rocket. Micro-payout economics remain viable at scale with tiered pricing; embedded verification satisfies AML without separate onboarding portals. Operations teams monitor success rates by method and city, optimizing routing when Bangladesh Bank rail maintenance affects specific endpoints. Contractor classification and tax reporting vary across Middle East & North Africa jurisdictions—TransFi transaction metadata supports finance teams documenting cross-border payments to Bangladesh individuals for regulatory filings in United Arab Emirates and peer markets. Payslip integrations can embed TransFi reference numbers so Bangladesh workers reconcile credits against expected BDT amounts on each pay cycle. Companies in Middle East & North Africa employing remote teams across Dhaka, Chittagong, Sylhet, Khulna, Rajshahi need recurring BDT salary delivery via bKash and Nagad. TransFi automates payroll batches with per-employee beneficiary KYC, webhook confirmation for HRIS integration, and transparent BHD-to-BDT FX disclosed before each run. Late payments damage employer brand in Bangladesh's competitive jute and agricultural exports labor market—particularly when workers compare offers from global platforms promising same-day wallet crediting.
Regional marketplaces connecting Middle East & North Africa buyers with Bangladesh sellers must settle earnings in BDT on weekly or daily cycles. TransFi validates seller Bangladesh account details before debit, supports split payments and commission deductions, and provides per-payout webhooks for automated reconciliation. Sellers in ready-made garments reinvest faster when bKash credits arrive within hours—not days through legacy correspondent chains that erode FX with hidden spreads. Affiliate networks and influencer platforms paying Bangladesh partners from Middle East & North Africa campaign budgets benefit from saved beneficiary profiles, scheduled sends, and shareable tracking links senders forward to recipients. Faster settlement reduces seller churn to domestic competitors and improves marketplace liquidity in categories from shipbuilding to microfinance and mobile money where working capital timing determines inventory availability for Middle East & North Africa promotional peaks. Escrow and holdback workflows common in cross-border marketplace disputes integrate with TransFi partial release APIs—funds remain in orchestrated custody until Middle East & North Africa buyers confirm delivery of Bangladesh goods. This reduces chargeback-like conflicts when ready-made garments shipments cross long ocean lanes between Middle East & North Africa ports and Dhaka export zones. Regional marketplaces connecting Middle East & North Africa buyers with Bangladesh sellers must settle earnings in BDT on weekly or daily cycles. TransFi validates seller Bangladesh account details before debit, supports split payments and commission deductions, and provides per-payout webhooks for automated reconciliation. Sellers in ready-made garments reinvest faster when bKash credits arrive within hours—not days through legacy correspondent chains that erode FX with hidden spreads. Affiliate networks and influencer platforms paying Bangladesh partners from Middle East & North Africa campaign budgets benefit from saved beneficiary profiles, scheduled sends, and shareable tracking links senders forward to recipients. Faster settlement reduces seller churn to domestic competitors and improves marketplace liquidity in categories from shipbuilding to microfinance and mobile money where working capital timing determines inventory availability for Middle East & North Africa promotional peaks. Escrow and holdback workflows common in cross-border marketplace disputes integrate with TransFi partial release APIs—funds remain in orchestrated custody until Middle East & North Africa buyers confirm delivery of Bangladesh goods. This reduces chargeback-like conflicts when ready-made garments shipments cross long ocean lanes between Middle East & North Africa ports and Dhaka export zones. Regional marketplaces connecting Middle East & North Africa buyers with Bangladesh sellers must settle earnings in BDT on weekly or daily cycles. TransFi validates seller Bangladesh account details before debit, supports split payments and commission deductions, and provides per-payout webhooks for automated reconciliation. Sellers in ready-made garments reinvest faster when bKash credits arrive within hours—not days through legacy correspondent chains that erode FX with hidden spreads.
Insurers, NGOs, and enterprises in Middle East & North Africa disbursing claims, aid, bonuses, and stipends to Bangladesh beneficiaries across dispersed geography need verified, traceable BDT payouts. TransFi orchestrates cross-border funding with localized delivery to bKash for recipients without traditional bank access and to bank rails for higher-value corporate payments. Audit trails satisfy regulated disbursement programs; batch processing scales during peak periods including Corridor volumes intensify during Ramadan and Eid disbursement windows, Hajj-related travel payments, and Gulf fiscal quarters when procurement teams settle Asian supplier invoices. Bahraini distributors remitting to Bangladeshi RMG manufacturers rely on real-time status APIs and recipient notifications when funds credit bKash. Customer support teams resolve inquiries from single transaction logs spanning Middle East & North Africa origin debit through Bangladesh confirmation—improving satisfaction for beneficiaries expecting urgent BDT access for medical bills, education fees, and emergency expenses in Sylhet and rural communities. Humanitarian programs serving Bangladesh disaster-affected regions prioritize bKash reach when branch banking is disrupted—TransFi wallet termination maintains payout continuity when traditional bank rails face localized outages. Donor reporting dashboards aggregate disbursement totals by Bangladesh province for NGO compliance with Middle East & North Africa and international grant-maker requirements. Insurers, NGOs, and enterprises in Middle East & North Africa disbursing claims, aid, bonuses, and stipends to Bangladesh beneficiaries across dispersed geography need verified, traceable BDT payouts. TransFi orchestrates cross-border funding with localized delivery to bKash for recipients without traditional bank access and to bank rails for higher-value corporate payments. Audit trails satisfy regulated disbursement programs; batch processing scales during peak periods including Corridor volumes intensify during Ramadan and Eid disbursement windows, Hajj-related travel payments, and Gulf fiscal quarters when procurement teams settle Asian supplier invoices. Bahraini distributors remitting to Bangladeshi RMG manufacturers rely on real-time status APIs and recipient notifications when funds credit bKash. Customer support teams resolve inquiries from single transaction logs spanning Middle East & North Africa origin debit through Bangladesh confirmation—improving satisfaction for beneficiaries expecting urgent BDT access for medical bills, education fees, and emergency expenses in Sylhet and rural communities. Humanitarian programs serving Bangladesh disaster-affected regions prioritize bKash reach when branch banking is disrupted—TransFi wallet termination maintains payout continuity when traditional bank rails face localized outages. Donor reporting dashboards aggregate disbursement totals by Bangladesh province for NGO compliance with Middle East & North Africa and international grant-maker requirements.
Whatever your use case, TransFi moves money from Middle East & North Africa to Bangladesh.
Choose your specific origin country - 5 supported markets across Middle East & North Africa link to dedicated Middle East & North Africa → Bangladesh corridor pages.
Pick your origin country and start sending from Middle East & North Africa to Bangladesh.
Find the right route for your cross-border payments - search by country or region and open the corridor that matches your needs.
Send North America to Indonesia corridor
Send Latin America to Indonesia corridor
Send Africa to Indonesia corridor
Send Asia Pacific to Indonesia corridor
Send Europe to Indonesia corridor
Send Middle East & North Africa to Indonesia corridor
Send North America to Philippines corridor
Send Latin America to Philippines corridor
Send Africa to Philippines corridor
$5B+
transaction volume projected
2M+
users served globally
100+
enterprise clients
Global compliance coverage | Enterprise-grade infrastructure | 24/7 support
How fast can I send money from Middle East & North Africa to Bangladesh through TransFi?
Most Middle East & North Africa to Bangladesh transfers through TransFi settle within minutes to a few hours once compliance checks complete—far faster than three-to-five-day SWIFT chains. Speed depends on payout method: bKash and instant bank rails typically confirm fastest; larger B2B bank transfers may follow same-day schedules. TransFi monitors bKash, Nagad, BEFTN, Rocket availability continuously and notifies senders via webhook at each stage from United Arab Emirates origin debit through Bangladesh beneficiary credit. Peak periods including Corridor volumes intensify during Ramadan and Eid disbursement windows, Hajj-related travel payments, and Gulf fiscal quarters when procurement teams settle Asian supplier invoices are handled with elastic capacity so delivery SLAs hold under volume spikes from Bahraini distributors remitting to Bangladeshi RMG manufacturers programs. Exact timelines vary by amount, beneficiary verification tier, and rail maintenance windows governed by Bangladesh Bank. Sandbox testing lets product teams benchmark ETA before production launch for Middle East & North Africa to Bangladesh payout flows. Cut-off times for United Arab Emirates treasury funding may affect same-day Bangladesh delivery—TransFi displays estimated arrival before send confirmation so Bahraini distributors remitting to Bangladeshi RMG manufacturers teams set recipient expectations accurately. Most Middle East & North Africa to Bangladesh transfers through TransFi settle within minutes to a few hours once compliance checks complete—far faster than three-to-five-day SWIFT chains. Speed depends on payout method: bKash and instant bank rails typically confirm fastest; larger B2B bank transfers may follow same-day schedules. TransFi monitors bKash, Nagad, BEFTN, Rocket availability continuously and notifies senders via webhook at each stage from United Arab Emirates origin debit through Bangladesh beneficiary credit. Peak periods including Corridor volumes intensify during Ramadan and Eid disbursement windows, Hajj-related travel payments, and Gulf fiscal quarters when procurement teams settle Asian supplier invoices are handled with elastic capacity so delivery SLAs hold under volume spikes from Bahraini distributors remitting to Bangladeshi RMG manufacturers programs.
Which payout methods are supported for recipients in Bangladesh?
TransFi supports payout to bKash, Nagad, BEFTN, Rocket in Bangladesh. bKash is essential for wallet-first recipients across 173 million people; bank rails handle higher-value B2B payments to vendors in Dhaka, Chittagong, Sylhet, Khulna, Rajshahi. Method selection can be automated by amount, beneficiary type, and success-rate optimization—Bahraini distributors remitting to Bangladeshi RMG manufacturers teams configure defaults via API while allowing recipient preference where product design requires. Failed termination triggers automatic retry on alternate Bangladesh rails when configured. Inclusion improves when products support both wallet and bank paths: rural Bangladesh beneficiaries may prefer bKash agent networks while urban manufacturers expect instant bank credit. TransFi termination breadth reduces last-mile failure rates versus bank-only outbound providers. Beneficiary lookup validates Bangladesh wallet IDs and bank account formats before debit—reducing costly failed sends for Bahraini distributors remitting to Bangladeshi RMG manufacturers programs disbursing to first-time recipients across Sylhet and provincial areas. TransFi supports payout to bKash, Nagad, BEFTN, Rocket in Bangladesh. bKash is essential for wallet-first recipients across 173 million people; bank rails handle higher-value B2B payments to vendors in Dhaka, Chittagong, Sylhet, Khulna, Rajshahi. Method selection can be automated by amount, beneficiary type, and success-rate optimization—Bahraini distributors remitting to Bangladeshi RMG manufacturers teams configure defaults via API while allowing recipient preference where product design requires. Failed termination triggers automatic retry on alternate Bangladesh rails when configured. Inclusion improves when products support both wallet and bank paths: rural Bangladesh beneficiaries may prefer bKash agent networks while urban manufacturers expect instant bank credit. TransFi termination breadth reduces last-mile failure rates versus bank-only outbound providers.
What currencies can I fund sends from in Middle East & North Africa?
Senders fund from UAE dirham, Saudi riyal, Egyptian pound, Moroccan dirham, and Jordanian dinar across 15+ Middle East & North Africa markets, with conversion to Bangladeshi taka at disclosed live rates. Enterprises may also fund from USD, EUR, or stablecoin treasury accounts before BDT local delivery. Egyptian InstaPay and peer origin rails initiate the send leg; TransFi handles cross-border FX and Bangladesh termination in one orchestrated flow with upfront fee transparency. Treasury teams model all-in costs before batch runs to Dhaka vendor networks. Multi-currency funding suits Bahraini distributors remitting to Bangladeshi RMG manufacturers operations spanning several Middle East & North Africa entities—each can fund from local currency while TransFi consolidates BDT delivery through unified API credentials and reconciliation exports. Pre-funded corridor balances optional for high-volume Bahraini distributors remitting to Bangladeshi RMG manufacturers programs reduce per-transaction funding latency—especially during Corridor volumes intensify during Ramadan and Eid disbursement windows, Hajj-related travel payments, and Gulf fiscal quarters when procurement teams settle Asian supplier invoices when origin debit volume spikes across Middle East & North Africa. Senders fund from UAE dirham, Saudi riyal, Egyptian pound, Moroccan dirham, and Jordanian dinar across 15+ Middle East & North Africa markets, with conversion to Bangladeshi taka at disclosed live rates. Enterprises may also fund from USD, EUR, or stablecoin treasury accounts before BDT local delivery. Egyptian InstaPay and peer origin rails initiate the send leg; TransFi handles cross-border FX and Bangladesh termination in one orchestrated flow with upfront fee transparency. Treasury teams model all-in costs before batch runs to Dhaka vendor networks.
What compliance is required for Middle East & North Africa to Bangladesh transfers?
MENA-origin payments require alignment with local FX controls, sanctions screening expectations, and destination-country AML frameworks administered by regulators such as central banks and financial intelligence units. Destination rules from Bangladesh Bank require beneficiary verification aligned with Bangladesh payment system standards. TransFi implements tiered sender KYB, sanctions screening, and source-of-funds checks scaled to transaction size. Bahraini distributors remitting to Bangladeshi RMG manufacturers programs receive audit exports suitable for internal compliance review and external examinations without maintaining separate vendor relationships per rail. Enhanced due diligence triggers for high-value B2B sends are configurable—product teams balance conversion friction against regulatory expectations in both Middle East & North Africa origin markets and Bangladesh inbound frameworks. PEP and sanctions list updates propagate automatically—Bahraini distributors remitting to Bangladeshi RMG manufacturers compliance teams avoid manual screening gaps when paying Bangladesh suppliers on recurring schedules. MENA-origin payments require alignment with local FX controls, sanctions screening expectations, and destination-country AML frameworks administered by regulators such as central banks and financial intelligence units. Destination rules from Bangladesh Bank require beneficiary verification aligned with Bangladesh payment system standards. TransFi implements tiered sender KYB, sanctions screening, and source-of-funds checks scaled to transaction size. Bahraini distributors remitting to Bangladeshi RMG manufacturers programs receive audit exports suitable for internal compliance review and external examinations without maintaining separate vendor relationships per rail. Enhanced due diligence triggers for high-value B2B sends are configurable—product teams balance conversion friction against regulatory expectations in both Middle East & North Africa origin markets and Bangladesh inbound frameworks. PEP and sanctions list updates propagate automatically—Bahraini distributors remitting to Bangladeshi RMG manufacturers compliance teams avoid manual screening gaps when paying Bangladesh suppliers on recurring schedules.
Can businesses batch pay Bangladesh suppliers from Middle East & North Africa?
Yes. Batch APIs support Bahraini distributors remitting to Bangladeshi RMG manufacturers paying hundreds or thousands of Bangladesh suppliers, contractors, or marketplace sellers with per-recipient validation and webhook status. ERP integrations from SAP, NetSuite, and regional accounting platforms trigger BDT disbursements on invoice approval workflows. Proof-of-payment documents include reference fields for Bangladesh vendor AP reconciliation and Middle East & North Africa treasury audit trails. Split payments, commission deductions, and scheduled payroll cycles are supported on the same API—marketplace operators and multinational procurement teams scale Middle East & North Africa to Bangladesh disbursements without parallel integration projects. CSV upload and scheduled batch windows support finance teams migrating from manual Middle East & North Africa wire processes—validation reports flag invalid Bangladesh beneficiary rows before any funds move. Yes. Batch APIs support Bahraini distributors remitting to Bangladeshi RMG manufacturers paying hundreds or thousands of Bangladesh suppliers, contractors, or marketplace sellers with per-recipient validation and webhook status. ERP integrations from SAP, NetSuite, and regional accounting platforms trigger BDT disbursements on invoice approval workflows. Proof-of-payment documents include reference fields for Bangladesh vendor AP reconciliation and Middle East & North Africa treasury audit trails. Split payments, commission deductions, and scheduled payroll cycles are supported on the same API—marketplace operators and multinational procurement teams scale Middle East & North Africa to Bangladesh disbursements without parallel integration projects. CSV upload and scheduled batch windows support finance teams migrating from manual Middle East & North Africa wire processes—validation reports flag invalid Bangladesh beneficiary rows before any funds move. Yes. Batch APIs support Bahraini distributors remitting to Bangladeshi RMG manufacturers paying hundreds or thousands of Bangladesh suppliers, contractors, or marketplace sellers with per-recipient validation and webhook status.
How does TransFi pricing work for the Middle East & North Africa to Bangladesh corridor?
TransFi pricing combines disclosed FX margins and per-transaction fees shown before send confirmation—no hidden correspondent charges. Rates vary by volume tier, payout method, and funding currency from Middle East & North Africa. High-throughput Bahraini distributors remitting to Bangladeshi RMG manufacturers programs receive dedicated rate cards and SLAs; contact TransFi for Middle East & North Africa to Bangladesh corridor pricing aligned to your payout mix across bKash and bank termination. Transparent all-in pricing helps finance teams compare TransFi against legacy wire desks and competitor products on delivered BDT value—not headline rates that hide FX spread. Volume commitments unlock improved economics for enterprise send programs. Dedicated account managers support enterprise Bahraini distributors remitting to Bangladeshi RMG manufacturers implementations with corridor playbooks, beneficiary onboarding UX review, and quarterly business reviews covering Bangladesh rail performance metrics. TransFi pricing combines disclosed FX margins and per-transaction fees shown before send confirmation—no hidden correspondent charges. Rates vary by volume tier, payout method, and funding currency from Middle East & North Africa. High-throughput Bahraini distributors remitting to Bangladeshi RMG manufacturers programs receive dedicated rate cards and SLAs; contact TransFi for Middle East & North Africa to Bangladesh corridor pricing aligned to your payout mix across bKash and bank termination. Transparent all-in pricing helps finance teams compare TransFi against legacy wire desks and competitor products on delivered BDT value—not headline rates that hide FX spread. Volume commitments unlock improved economics for enterprise send programs. Dedicated account managers support enterprise Bahraini distributors remitting to Bangladeshi RMG manufacturers implementations with corridor playbooks, beneficiary onboarding UX review, and quarterly business reviews covering Bangladesh rail performance metrics.
Fast, transparent, and built for modern cross-border payments from Middle East & North Africa to Bangladesh
 Global Payments. Delivered Locally - Send, receive, and convert funds across 100+ countries.UAE
 USA
 Poland
 Canada
 Bahamas
 Indonesia
 Australia
 Copyright ©2026 TransFi | All Rights Reserved