


Settlement speed
Most transfers to Bangladesh settle in minutes to hours via local rails — not days through correspondent banks.
Tumanggap ng bayad sa Bangladeshi taka mula sa mga pandaigdigang customer, partner, at platform na may buong visibility at mas mabilis na settlement na idinisenyo para sa Bangladesh, pinapagana ng TransFi.
Mabilis na SettlementGinawa para sa mas mabilis na paghahatid papuntang Bangladesh
Malinaw na PresyoAlamin ang bayarin at FX rate bago ka magpadala
Pandaigdigang AbotTumanggap mula sa 70+ na bansa gamit ang mga lokal na payout rail
 USD
 BDT
Receive in Bangladesh from USA with payout timing shown before you collect on supported rails.
Most supported routes settle within minutes to hours via local rails and stablecoin infrastructure.
Live FX and fees on every USA → Bangladesh route — no hidden spreads or surprise deductions.
Know the final amount, fees, and FX rate before funds leave USA or arrive in Bangladesh.
Track every collection into Bangladesh from USA with full status visibility from initiation to local payout.
Corridor-level status updates from initiation through local payout in Bangladesh.
Speed up USA → Bangladesh settlement with stablecoin infrastructure bridging both markets.
Combine local payment rails in USA with faster settlement into Bangladesh payout networks.
Most transfers to Bangladesh settle in minutes to hours via local rails — not days through correspondent banks.
See exchange rates and fees upfront before you confirm a transfer on the USA to Bangladesh corridor.
Real-time status updates from funding in USA through delivery in Bangladesh.
Collect through localized payment rails in Bangladesh, with settlement routed back to your USA treasury.
KYC, KYB, and beneficiary verification aligned with regulations on both sides of the corridor.
Fund collections from payers in USA using familiar local payment methods.
Collect payments across USA and Bangladesh with full visibility.
Ibahagi ang iyong Bangladeshi taka collection details sa mga payer sa USA
Nagpapadala ang mga payer ng pondo gamit ang local payment methods sa kanilang bansa
I-track ang incoming payments at settlement status nang real-time
Tumanggap ng pondo sa Bangladesh via local payout rails
Start receiving from USA in just a few steps.
Ang bKash ang dominant mobile financial service ng Bangladesh na may higit sa 65 milyong registered account at pinakamalawak na agent network sa bansa. Umaasa ang mga user sa bKash para sa P2P transfer, merchant QR payment, utility bill, school fee, at e-commerce checkout. Para sa business, ang bKash ay madalas ang single highest-impact payment method na i-integrate —ang brand nito ay synonymous sa mobile money sa Bangladesh, at ang kawalan nito sa checkout ay direktang conversion penalty. Ang international send at receive product na nagtatapos sa bKash ay tumutugma sa UX expectation ng pinakamalaking financial user base ng Bangladesh.
Minutes
Ang Nagad ay mobile financial service ng Bangladesh Post Office at primary competitor ng bKash, na may mabilis na adoption dahil sa government disbursement, social safety net payment, at competitive merchant incentive. Mahusay ang Nagad sa pag-abot sa user sa semi-urban at rural area kung saan mahalaga ang post office brand trust —lalo na para sa remittance receive sa Sylhet, Rangpur, at coastal district. Ang mga platform na sumusuporta sa bKash at Nagad ay pinapakinabangan ang addressable market coverage sa 172 milyong populasyon ng Bangladesh at iniiwasan ang pag-alienate sa user na loyal sa alinmang wallet ecosystem.
Minutes
Ang Rocket, na pinapatakbo ng Dutch-Bangla Bank, ay isa sa pioneering MFS platform ng Bangladesh na may malalim na ugat sa bank-linked mobile banking sa 172 milyong populasyon. Nananatiling popular ito sa mga user na mas gusto ang bank-backed wallet at sa ilang merchant category sa Dhaka at Chattogram. Sinusuportahan ng Rocket ang cash-in at cash-out sa pamamagitan ng DBBL agent at ATM, kaya reliable rail ito para sa RMG payroll-adjacent flow at user na nagta-transition sa pagitan ng cash at digital money sa export economy ng Bangladesh.
Minutes to hours
Mahalaga pa rin ang commercial bank transfer para sa B2B settlement, property transaction, at higher-value consumer payment. Ang mga nangungunang institusyon kabilang ang BRAC Bank, City Bank, at Islami Bank Bangladesh ay naglilingkod sa corporate treasury, exporter, at middle-class account holder. Para sa international platform, ang pagsuporta sa bank transfer collection at payout sa BDT ay nagbibigay ng critical backstop para sa transaction na lumalampas sa MFS limit o nangangailangan ng formal banking record.
Same business day
Ang Upay ay lumalaking mobile financial service na sinusuportahan ng United Commercial Bank, na tumutok sa digital-native user at merchant partnership sa $4.8 bilyon e-commerce market ng Bangladesh. Mas maliit man kaysa bKash at Nagad, nagdadagdag ang Upay ng incremental coverage sa mga UCB customer at urban professional sa Dhaka. Ang pagsasama ng Upay sa multi-rail strategy ay naghahanda sa payment acceptance habang patuloy na nagdi-diversify ang MFS market ng Bangladesh lampas sa dalawang dominant player na naglilingkod sa ikapitong pinakamalaking remittance receiver nation.
Minutes to hours
Get paid with the payment methods customers prefer in Bangladesh.
This USA to Bangladesh route combines TransFi's cross-border infrastructure with deep local payment coverage in Bangladesh. Whether you are disbursing payroll, paying suppliers, or collecting from customers, you get transparent FX, real-time tracking, and payout rails built for how people actually move money on this corridor.
See how you can collect payments in Bangladesh from USA.
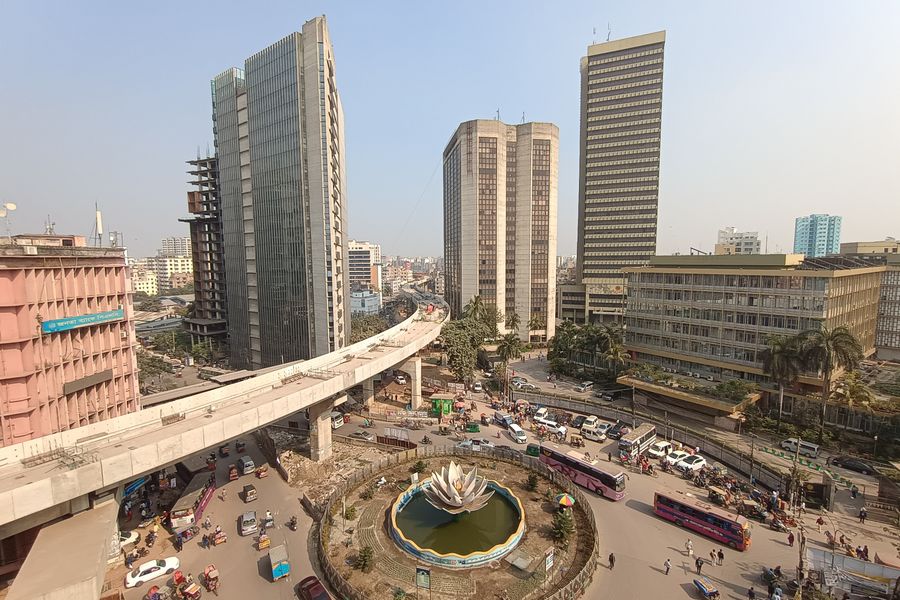
Bangladeshi businesses increasingly collect revenue from payers across internasyonal—Malaysian sourcing companies, Australian importers, Chinese textile traders, Singaporean technology clients, and regional marketplace buyers who expect frictionless payment while Bangladeshi merchants receive settled funds in BDT. With 170 million consumers, the world's second-largest garment export sector, and bKash-dominated mobile money adoption, receive-money flows from internasyonal represent a critical revenue channel for Dhaka tech firms, Chittagong logistics operators, and garment manufacturers across export processing zones.
International merchants frequently lose Bangladeshi sales because checkout supports only foreign-issued cards that local banks decline for cross-border transactions. Bangladeshi customers expect bKash and Nagad wallet payment—not foreign card entry with high failure rates. Bangladeshi garment exporters invoicing Malaysian and Chinese buyers need receive infrastructure presenting localized BDT collection through mobile money alongside structured cross-border payment paths. TransFi bridges this gap for internasyonal-facing Bangladeshi merchants.
TransFi allows Bangladeshi merchants to present bKash, Nagad, and Rocket payment options through a single integration, collecting taka through trusted domestic rails while settling to treasury in BDT, USD, or other preferred currencies. Compliance, FX, and reconciliation operate within the same orchestration infrastructure used for outbound sends. Platforms collecting garment export payments, IT service invoices, logistics fees, or marketplace charges from internasyonal partners gain conversion rates aligned with Bangladeshi payment norms.
For Bangladeshi companies scaling garment exports and IT services across internasyonal, TransFi's unified API avoids rebuilding payment stacks per corridor—one integration pattern covers receive and send across the internasyonal region.
Product and finance leaders should treat localized receive capability as a growth lever, not a compliance checkbox. When checkout mirrors domestic wallet and bank-transfer habits, authorization rates rise, support tickets fall, and marketing teams can confidently scale acquisition in the destination country. TransFi pairs localized collection with settlement flexibility—holding balances locally where useful, or converting on a schedule that matches treasury policy—so receive flows strengthen unit economics rather than adding reconciliation burden.
Customer experience teams also gain leverage when payment confirmation is instant and branded consistently across web, mobile, and invoice channels. Reducing payment friction at the moment of highest intent—checkout, subscription renewal, or invoice settlement—directly improves conversion and cash-flow predictability. TransFi's receive flows are designed to surface clear payer messaging, reliable success states, and finance-grade reconciliation data in the same integration.
Join businesses receiving payments in Bangladesh from USA with TransFi.
Bangladeshi businesses increasingly collect revenue from payers across internasyonal—Malaysian sourcing companies, Australian importers, Chinese textile traders, Singaporean technology clients, and regional marketplace buyers who expect frictionless payment while Bangladeshi merchants receive settled funds in BDT. With 170 million consumers, the world's second-largest garment export sector, and bKash-dominated mobile money adoption, receive-money flows from internasyonal represent a critical revenue channel for Dhaka tech firms, Chittagong logistics operators, and garment manufacturers across export processing zones.
Understand what drives this corridor — then start receiving in Bangladesh from USA.
Three things that define this route
International merchants frequently lose Bangladeshi sales because checkout supports only foreign-issued cards that local banks decline for cross-border transactions. Bangladeshi customers expect bKash and Nagad wallet payment—not foreign card entry with high failure rates. Bangladeshi garment exporters invoicing Malaysian and Chinese buyers need receive infrastructure presenting localized BDT collection through mobile money alongside structured cross-border payment paths. TransFi bridges this gap for internasyonal-facing Bangladeshi merchants.
Mobile financial services dominate Bangladeshi consumer and worker payment behavior, with bKash reaching over 70 million registered accounts. Cross-border receive must accommodate wallet-first collection for B2C transactions while supporting bank transfer for enterprise garment trade invoicing. Bangladesh Bank regulatory oversight benefits merchants integrating through compliant orchestration partners who handle payer identification and cross-border settlement reporting requirements.
TransFi allows Bangladeshi merchants to present bKash, Nagad, and Rocket payment options through a single integration, collecting taka through trusted domestic rails while settling to treasury in BDT, USD, or other preferred currencies. Compliance, FX, and reconciliation operate within the same orchestration infrastructure used for outbound sends. Platforms collecting garment export payments, IT service invoices, logistics fees, or marketplace charges from internasyonal partners gain conversion rates aligned with Bangladeshi payment norms.
From payouts and collections to checkout, treasury, and stablecoin rails — TransFi powers it all through a single integration.
Apparel manufacturers across Gazipur, Ashulia, and Chittagong billing Malaysian sourcing agents, Hong Kong trading companies, and Australian retailers benefit from receive flows supporting bank transfer collections and structured cross-border payment requests. TransFi generates trackable payment instructions with webhook status updates for export finance teams. internasyonal buyers appreciate clear payment paths while Bangladeshi manufacturers reconcile inbound transfers against purchase orders and shipment milestones. TransFi provides webhook confirmation, reference tagging, and reconciliation-friendly status events so finance teams can automate exception handling and month-end close without manual bank portal checks.
Software development houses, fintech startups, and BPO operators across Dhaka billing Singaporean and Malaysian enterprises benefit from receive flows supporting bKash collections from domestic clients and structured cross-border invoicing for internasyonal accounts receivable. TransFi enables BDT-priced service collections with settlement to developer treasury in USD, reducing friction for Bangladesh's growing IT export sector. TransFi provides webhook confirmation, reference tagging, and reconciliation-friendly status events so finance teams can automate exception handling and month-end close without manual bank portal checks.
Bangladeshi direct-to-consumer brands, handicraft exporters, and specialty retailers marketing to Malaysian and Australian customers need checkout presenting bKash and Nagad for domestic buyers. TransFi enables BDT collection through localized methods while supporting cross-border settlement. Cart abandonment drops when Bangladeshi storefronts present familiar mobile wallet options matching domestic marketplace experiences. TransFi provides webhook confirmation, reference tagging, and reconciliation-friendly status events so finance teams can automate exception handling and month-end close without manual bank portal checks.
Freight forwarders, port operators, and supply chain service providers across Chittagong billing internasyonal trading partners need efficient BDT collection through bank transfer and mobile money with settlement visibility for export finance operations. TransFi supports inbound collections from Bangladeshi payers via bKash while enabling structured receive from regional counterparties with invoice-level reconciliation. TransFi provides webhook confirmation, reference tagging, and reconciliation-friendly status events so finance teams can automate exception handling and month-end close without manual bank portal checks.
Whatever your use case, TransFi helps you collect payments in Bangladesh from USA.

Ibahagi ang detalye ng bangko para direktang makatanggap ng bayad

Humiling ng bayad sa pamamagitan ng ligtas na link

Tumanggap ng bayad gamit ang QR code

Magpadala ng request sa mga kliyente, team, o partner
Accept payments from USA through familiar local rails.
Magpadala at tumanggap via bKash, Nagad, and Bangladeshi bank transfers — ang mga method na ginagamit na ng mga tao sa Bangladesh araw-araw.
Most transfers involving Bangladesh settle within minutes via instant payment networks and mobile wallets.
See the exact exchange rate and fees before you send — no hidden spreads on Bangladesh payment routes.
Whether paying vendors, contractors, or family, TransFi routes BDT through compliant local infrastructure in Bangladesh.
$5B+
inaasahang transaction volume
2M+
user na pinagsisilbihan sa buong mundo
100+
enterprise na kliyente
Pandaigdigang saklaw ng compliance | Imprastrukturang pang-enterprise | Suportang 24/7
Find the right route for your cross-border payments — search by country or region and open the corridor that matches your needs.

Tumanggap ng pera mula sa Indonesia

Tumanggap ng pera mula sa Philippines

Tumanggap ng pera mula sa Malaysia

Tumanggap ng pera mula sa Thailand

Tumanggap ng pera mula sa Pakistan
Tumanggap ng pera mula sa Bangladesh
Tumanggap ng pera mula sa USA

Tumanggap ng pera mula sa China

Tumanggap ng pera mula sa Brazil

Tumanggap ng pera mula sa India
Which Bangladeshi payment methods should internasyonal-facing merchants enable?
Prioritize bKash and Nagad for consumer and worker payments—the mobile wallets reaching Bangladesh's broadest user base. For B2B garment trade receive from internasyonal corporate clients, bank transfer and invoice-based collection flows perform best. TransFi lets Bangladeshi merchants configure enabled methods through API based on customer segment, transaction value, and export category. Implementation typically follows TransFi's standard sandbox-to-production path with KYB onboarding, method enablement, and test transactions before live traffic.
How does FX work when receiving BDT payments from internasyonal?
Customers typically pay in Bangladeshi taka through bKash, Nagad, or bank transfer while TransFi applies agreed FX conversion for settlement to the merchant's designated currency. Cross-border internasyonal payments from garment buyers may involve USD or MYR conversion depending on trade terms. Rates and fees are disclosed at configuration time so Bangladeshi finance teams can forecast export revenue. Implementation typically follows TransFi's standard sandbox-to-production path with KYB onboarding, method enablement, and test transactions before live traffic.
Can Bangladeshi garment exporters receive payments from Chinese and Malaysian buyers?
TransFi supports structured cross-border receive from internasyonal trading partners with transparent FX and BDT settlement to Bangladeshi exporter accounts. For domestic collections from local agents and workers, bKash and Nagad provide familiar mobile wallet checkout. Export finance teams benefit from invoice reference tagging and webhook status updates for shipment-linked payment reconciliation. Implementation typically follows TransFi's standard sandbox-to-production path with KYB onboarding, method enablement, and test transactions before live traffic.
Is TransFi suitable for high-volume Bangladesh receive from internasyonal trade?
Yes. TransFi's infrastructure supports platform-scale volume across Bangladeshi garment export, logistics, and IT services receive flows. Webhooks, idempotent API design, and reconciliation exports maintain operational visibility for manufacturers processing multiple internasyonal buyer payments simultaneously. Compliance-ready infrastructure aligns with Bangladesh Bank oversight requirements for cross-border trade settlement. Implementation typically follows TransFi's standard sandbox-to-production path with KYB onboarding, method enablement, and test transactions before live traffic.
Mabilis, transparent, at maaasahang cross-border collections sa Bangladesh
 Global na Pagbabayad. Inihahatid nang Lokal - Subukan at maging bahagi ng global payment revolution ngayon!
 UAEUSA
 Poland
 Canada
 BahamasIndonesia
 Australia
 Copyright ©2026 TransFi | Lahat ng Karapatan ay Nakalaan


